The GIC Trap: High Interest and No Deduction from 1 July
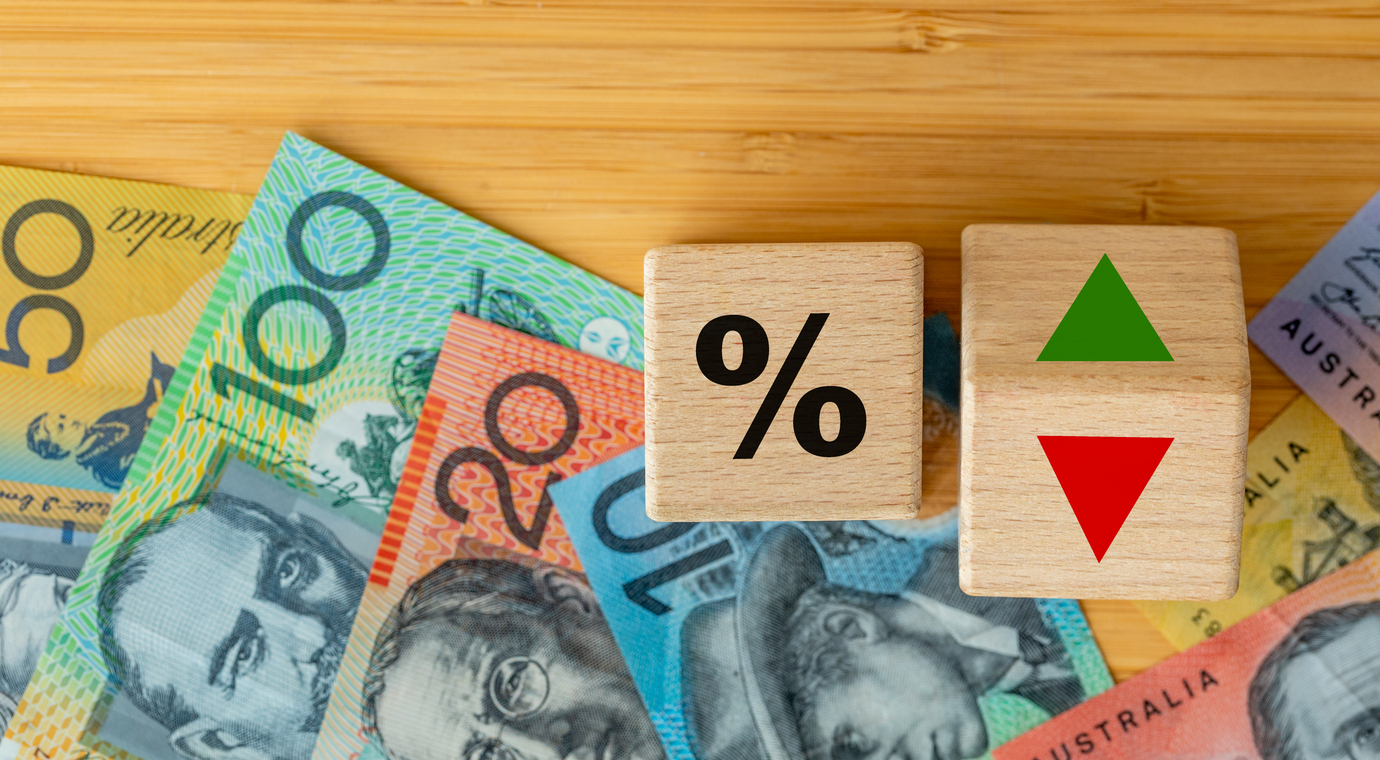
If you’ve ever paid your tax late, you’ll be familiar with the ATO’s General Interest Charge (GIC).
Until recently, you could claim that interest as a tax deduction. But not anymore (starting 1 July 2025).
Here’s everything business owners and sole traders need to know, and what to do now so you don’t get stung later.
What Is the ATO’s General Interest Charge (GIC)?
The ATO applies GIC to any unpaid tax liabilities. This could include:
- Late income tax payments
- Underpaid instalments (BAS, PAYG, IAS)
- Amended or corrected returns that result in a shortfall
GIC is charged daily and compounded, meaning the longer you leave it, the more it grows.
Until now, you could claim GIC as a tax deduction in your return for the year it was incurred.
What’s Changing from 1 July 2025?
Starting 1 July 2025, you can no longer claim tax deductions for:
- ATO General Interest Charges (GIC)
- Shortfall Interest Charges (SIC) from amended assessments
This applies to
- all taxpayers — businesses and individuals.
- All interest — both recent bills and debt from past years (for interest incurred after 1 July 2025)
Why This Matters
Late tax payments have always come with a cost — but that cost is about to get a lot steeper.
Here’s why:
Late Tax = High-Interest Loan
Once the GIC deduction is removed, paying late is like taking out a business loan at 15–16% interest — only without the benefits.
That’s more than most business overdrafts or credit cards.
When cash is tight we often prioritise paying for what’s urgent, and keeping the gears turning. It’s tempting to delay ATO payments, because they’re not affecting you right now.
But some problems that appear manageable now can carry longer-term damage.. And this new change makes late payments a lot more expensive. And with daily compounding the expense stacks up very quickly.
That’s why it’s more important than ever to stay on top of ATO deadlines and manage ATO debt.
Who’s Most at Risk (and What to Do)
1. Business owners with seasonal cash flow
Risk: Unpredictable income leads to missed ATO payments
What to do: Forecast tax and prepare early
We can help:
- Predict BAS, GST, Super and income tax payments
- Lodge on time and avoid interest altogether
- Set reminders and alerts so nothing slips through
2. Sole traders who often miss lodgement deadlines
Risk: Small missed deadlines snowball into big interest bills
What to do: Set calendar alerts and pay promptly
We can help:
- Simplify your record-keeping
- Keep your ATO account up to date
- Make tax time faster and easier
3. Anyone with ATO payment plans or old debts
Risk: GIC builds daily on existing balances
What to do: Pay off what you can before 30 June 2025
We can help:
- Build a strategy to pay off your deb
- Request the ATO for a waiver in some circumstances.
- Negotiate with the ATO on your behalf if needed
4. Businesses with trusts, SMSFs, or multiple entities
Risk: Multiple reporting dates means higher risk of accidental late payments
What to do: Stay organised and track deadlines
How we help:
- Monitor all your lodgement obligations
- Ensure no returns are forgotten
- Handle lodgements across all entities
What Can You Do Right Now?
✅ Check if you have any unpaid ATO debts
✅ Pay off what you can before 30 June 2025
✅ Ask us to help request a waiver if your situation qualifies
✅ Set up systems to avoid late payments moving forward
Need Help Managing ATO Interest or Deadlines?
We help small business owners and busy founders stay ahead of tax changes, avoid interest, and protect their cash.
We may also be able to recommend financing options to make life easier in these circumstances.
Whether you need a one-off check-up or ongoing support — we’ve got you covered.
Book a Free Tax Check-In
Contact us and let’s keep your money where it belongs — in your business.