Payday Super Has Arrived – What Employers Need to Know
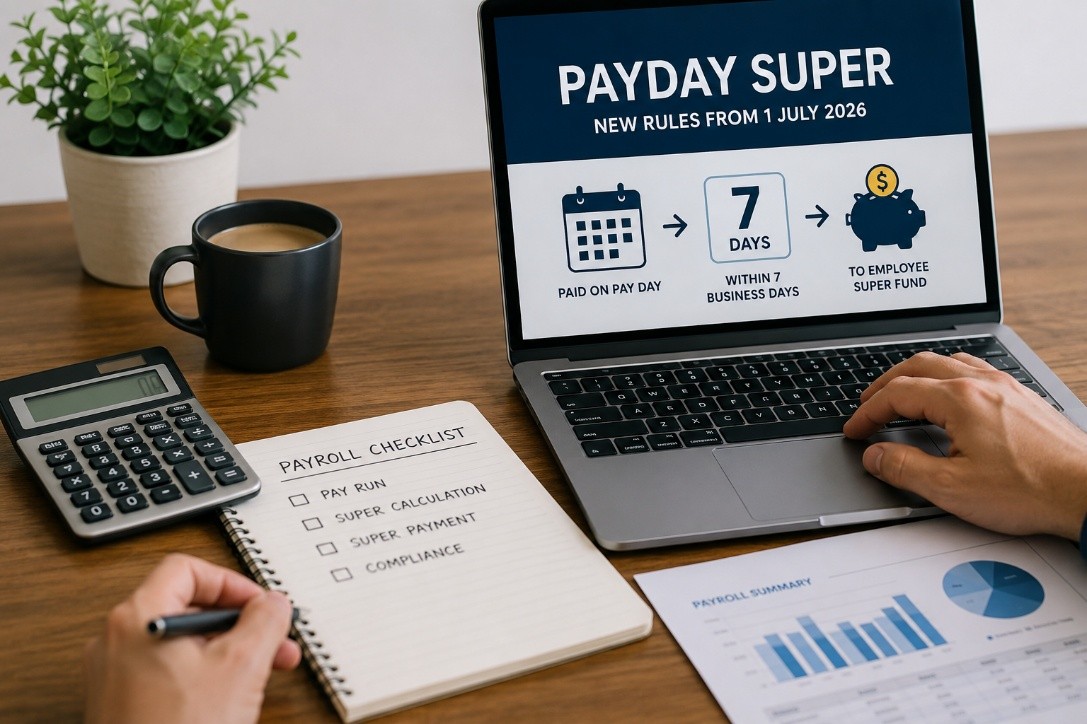
From 1 July 2026, the way employers pay super has officially changed. If your business has been making super contributions every quarter, it’s time to adjust. Under the new Payday Super rules, super must now be paid much sooner—within seven business days of each payday.
While the change is designed to help employees receive their super faster, it also means employers need to stay on top of payroll processes and cash flow.
What Is Payday Super?
Previously, employers generally had until 28 days after the end of each quarter to pay super contributions.
Now, every payday starts the countdown. Super contributions must be received by your employee’s super fund within seven business days of paying wages.
This applies to most salary and wage payments, including commissions, bonuses and some contractor payments.
Why Has This Changed?
The Australian Government introduced Payday Super to:
- Help employees receive their super sooner.
- Reduce unpaid or late super.
- Improve retirement savings over time.
- Increase transparency and compliance.
Although the goal is positive, businesses may need to update their payroll systems and processes to keep up with the new requirements.
What Employers Need to Know
There are a few important changes to be aware of:
- Super must reach the employee’s fund within seven business days of payday.
- Super shortfalls are now assessed for each payday, rather than quarterly.
- The ATO’s Small Business Superannuation Clearing House has closed, so businesses using it will need a SuperStream-compliant alternative.
- Penalties for late payments are tougher, although businesses that make genuine efforts to comply and fix mistakes quickly may receive a more practical approach from the ATO during the first year.
Watch Out for the June–July Transition
The move to Payday Super creates a unique situation for employers during July 2026.
If you still owe super for the June 2026 quarter, any contributions made from 1 July 2026 onwards may first be applied to that outstanding amount before counting towards your new Payday Super obligations.
Depending on your July payroll dates, this could unintentionally create a super shortfall.
If you’re unsure how the timing affects your business, it’s worth seeking advice before processing your July payments.
Three Steps You Can Take Now
1. Check Your Payroll System
Make sure your payroll software and super payment processes are ready for Payday Super. Review your pay codes and ensure super contributions are being calculated correctly.
2. Review Your Cash Flow
Because super is now paid much more frequently, your cash flow may look different. Consider how this change affects your budgeting and payment approvals.
3. Keep Your Team Informed
Ensure your payroll and finance teams understand the new rules and regularly review your processes. Small mistakes can quickly become larger compliance issues if they go unnoticed.
We’re Here to Help
Payday Super is one of the biggest changes to Australia’s superannuation system in years. With the right systems and processes in place, businesses can make the transition smoothly and remain compliant.
If you have questions about how the new rules apply to your business, or you’d like help reviewing your payroll processes, contact your adviser at [Your Firm Name]. We’re here to help you identify any gaps and ensure your business is ready for Payday Super.
Call us at 07 34830100 or send a message if we can help